Every few weeks someone calls us about a house in Akron or Cuyahoga Falls and opens with the same sentence: "I had it listed, two buyers fell through, and my agent says I should just find a cash buyer." Then they ask what that actually means, because the only thing they know about cash buyers is the bandit signs on the telephone poles.
We buy houses in Summit County for cash and keep them as rentals, so this is the inside view. Here is how cash home buyers work in Ohio, why a bank will not lend on a lot of the houses we buy, what that is worth to you as a seller, and how to tell a real buyer from someone who is just going to shop your house to one.
What a cash buyer actually is
A cash home buyer is a company or a person that buys the house with its own money, closes through a title company, and does not need an appraisal, an inspection contingency, or a lender's approval to do it. In Ohio the deal still runs through the normal machinery: a purchase agreement, a title search, a deed recorded at the county, and the state and county conveyance fee paid at closing. What is missing is the bank, and the bank is where most of the delay, the conditions, and the fall-throughs come from.
There are three kinds of companies that call themselves cash buyers, and they are not the same thing:
- Flippers buy, renovate in 60 to 90 days, and resell on the open market. Their offer has to cover a real estate commission on the way back out.
- Buy-and-hold investors buy, renovate, and keep the house as a rental. No resale costs, which is why the math can land a little higher. That is us. Here is what actually happens to your house after you sell it to us.
- Wholesalers do not buy anything. They get your house under contract and then sell that contract to one of the first two, keeping the spread. If the buyer they find backs out, so do they.
The rest of this post is about the first two. Our process page walks through what a sale with us looks like step by step.
Why a bank will not finance a lot of Ohio houses
This is the part most sellers have never been told, and it is the real reason cash buyers exist.
A mortgage is not just a loan to the buyer. The house is the collateral, and the lender sends an appraiser to confirm the collateral is safe, sound, and worth the money. FHA loans follow HUD's minimum property requirements. Conventional loans follow Fannie Mae and Freddie Mac condition standards plus whatever extra rules the individual lender adds. Either way, the appraiser walks the house with a checklist, and a lot of older Summit County houses fail it.
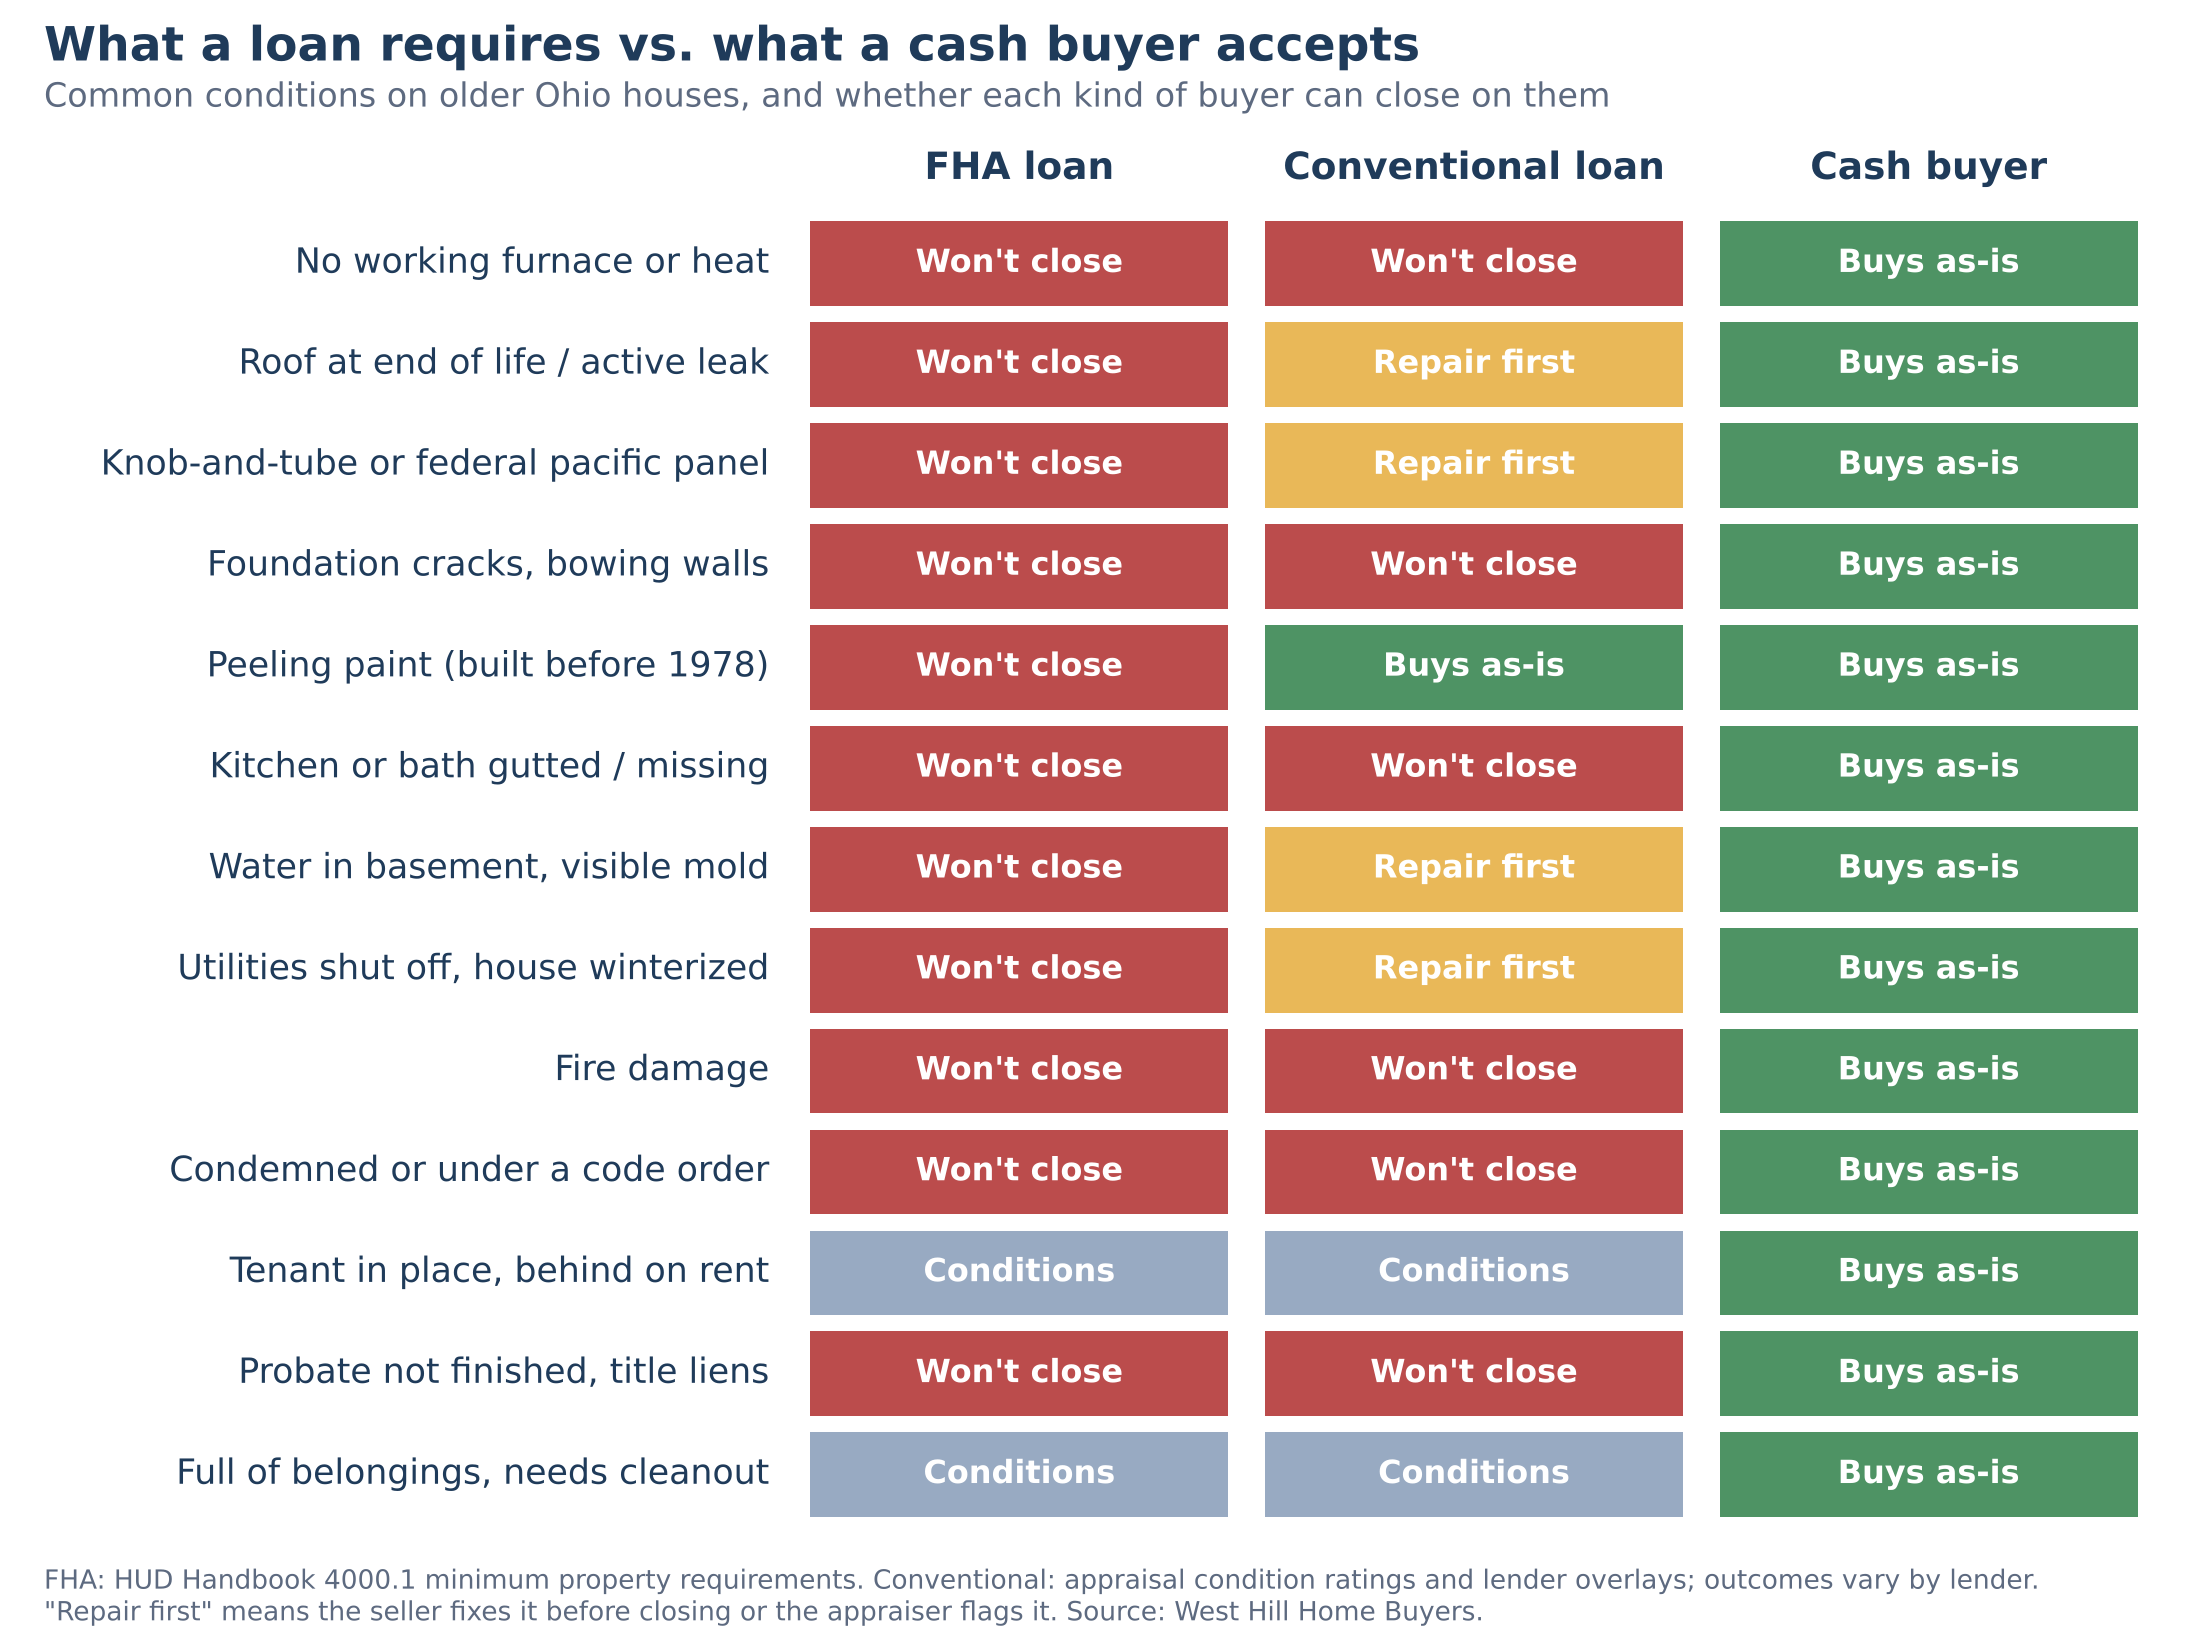
Here is what blocks a loan in practice. We see every one of these on houses in Kenmore, Goodyear Heights, and Cuyahoga Falls every month.
- No working heat. An FHA appraiser has to confirm the furnace runs. A house that has been winterized with the gas off cannot be appraised until the utilities are back on and somebody has tested the systems. If the furnace is dead, the appraisal comes back "subject to repair" and the buyer's loan is stuck until it is replaced.
- Roof at the end of its life. FHA wants at least two years of remaining life. A roof with active leaks fails on both FHA and conventional.
- Peeling paint on a house built before 1978. On FHA this alone kills the deal until it is scraped and repainted, because of lead paint rules. Half the housing stock in Akron was built before 1950.
- Old electrical. Knob-and-tube wiring and certain old panels get flagged as safety issues. Most lenders also cannot get the buyer homeowners insurance on them, and no insurance means no loan.
- Foundation problems. Bowing block walls, which are everywhere in Summit County's older basements, get the appraisal flagged for a structural engineer. Buyers walk.
- Gutted kitchen or bath. A house has to be habitable to appraise. No functioning kitchen means no FHA or conventional loan, full stop.
- Water and mold. Visible mold or standing water in the basement gets written up and has to be remediated first.
- Fire damage. Nobody lends on it. We wrote a separate guide on selling a fire-damaged house in Ohio, including how the insurance claim and the sale fit together.
- Condemned or under a code order. If the City of Akron has posted the house or issued an order to repair, a lender will not touch it until the order is cleared. We covered how repair orders and condemnation work in Akron, and we pulled two years of Housing Appeals Board records to see who actually owns Akron's condemned houses.
- Title problems. A house still sitting in a deceased parent's name, an unreleased lien, a tax certificate, an old second mortgage nobody paid off. A lender needs clean title at closing. A cash buyer can wait while an attorney clears it, or help pay to clear it. Our guide to selling an inherited house in Akron goes through the probate side.
Notice what all of those have in common. None of them are about what the house is worth. They are about whether a lender is willing to be on the hook for it. A perfectly good house with $30,000 of equity in it can be unfinanceable because of a dead furnace and some chipped paint on the porch.
The other half: work no normal buyer wants to take on
Say the house could technically be financed. There is a second filter, and it is the buyer's own stomach.
The people shopping for a house to live in with an FHA loan and 3.5% down do not have $50,000 in the bank for a roof, a furnace, a panel, and a sewer lateral. Even if they did, they do not have a crew, they do not know which permits Akron requires, and they are not going to spend their first six months in a house living through a gut renovation. They want to move in. That is the whole point of buying a house.
So a house that needs everything has a very short list of people who can actually buy it:
- Someone with the cash to close and the cash to renovate on top of it.
- Someone with contractors already lined up in a market where good trades are booked out for weeks.
- Someone who knows that a 1920s Akron bungalow with a wet basement is usually a downspout and grading problem, not a foundation problem, and is not afraid of it.
- Someone who can carry the house for six months with no rent coming in and still make the numbers work.
That is a short list, and it is why a tired house in Firestone Park can sit on the MLS for 60 days while a renovated one three streets over sells in ten. The buyers who could have bought the tired one with a loan cannot handle the work, and the buyers who can handle the work are not paying retail. We have done this on dozens of houses across Summit County, including a duplex that needed everything, and the first job on nearly every one was the systems nobody can see: plumbing, electrical, drainage, roof. The dry basement is the part we care most about.
A cash buyer adds value by being that short list. We are not doing you a favor, and we are not lowballing you. We are the only buyer the house has, and we are pricing in the work and the risk that a normal buyer will not take.
How the offer gets calculated
Every legitimate cash buyer in Ohio runs the same arithmetic. Start with what the house will be worth after it is fixed, then subtract everything it takes to get there.
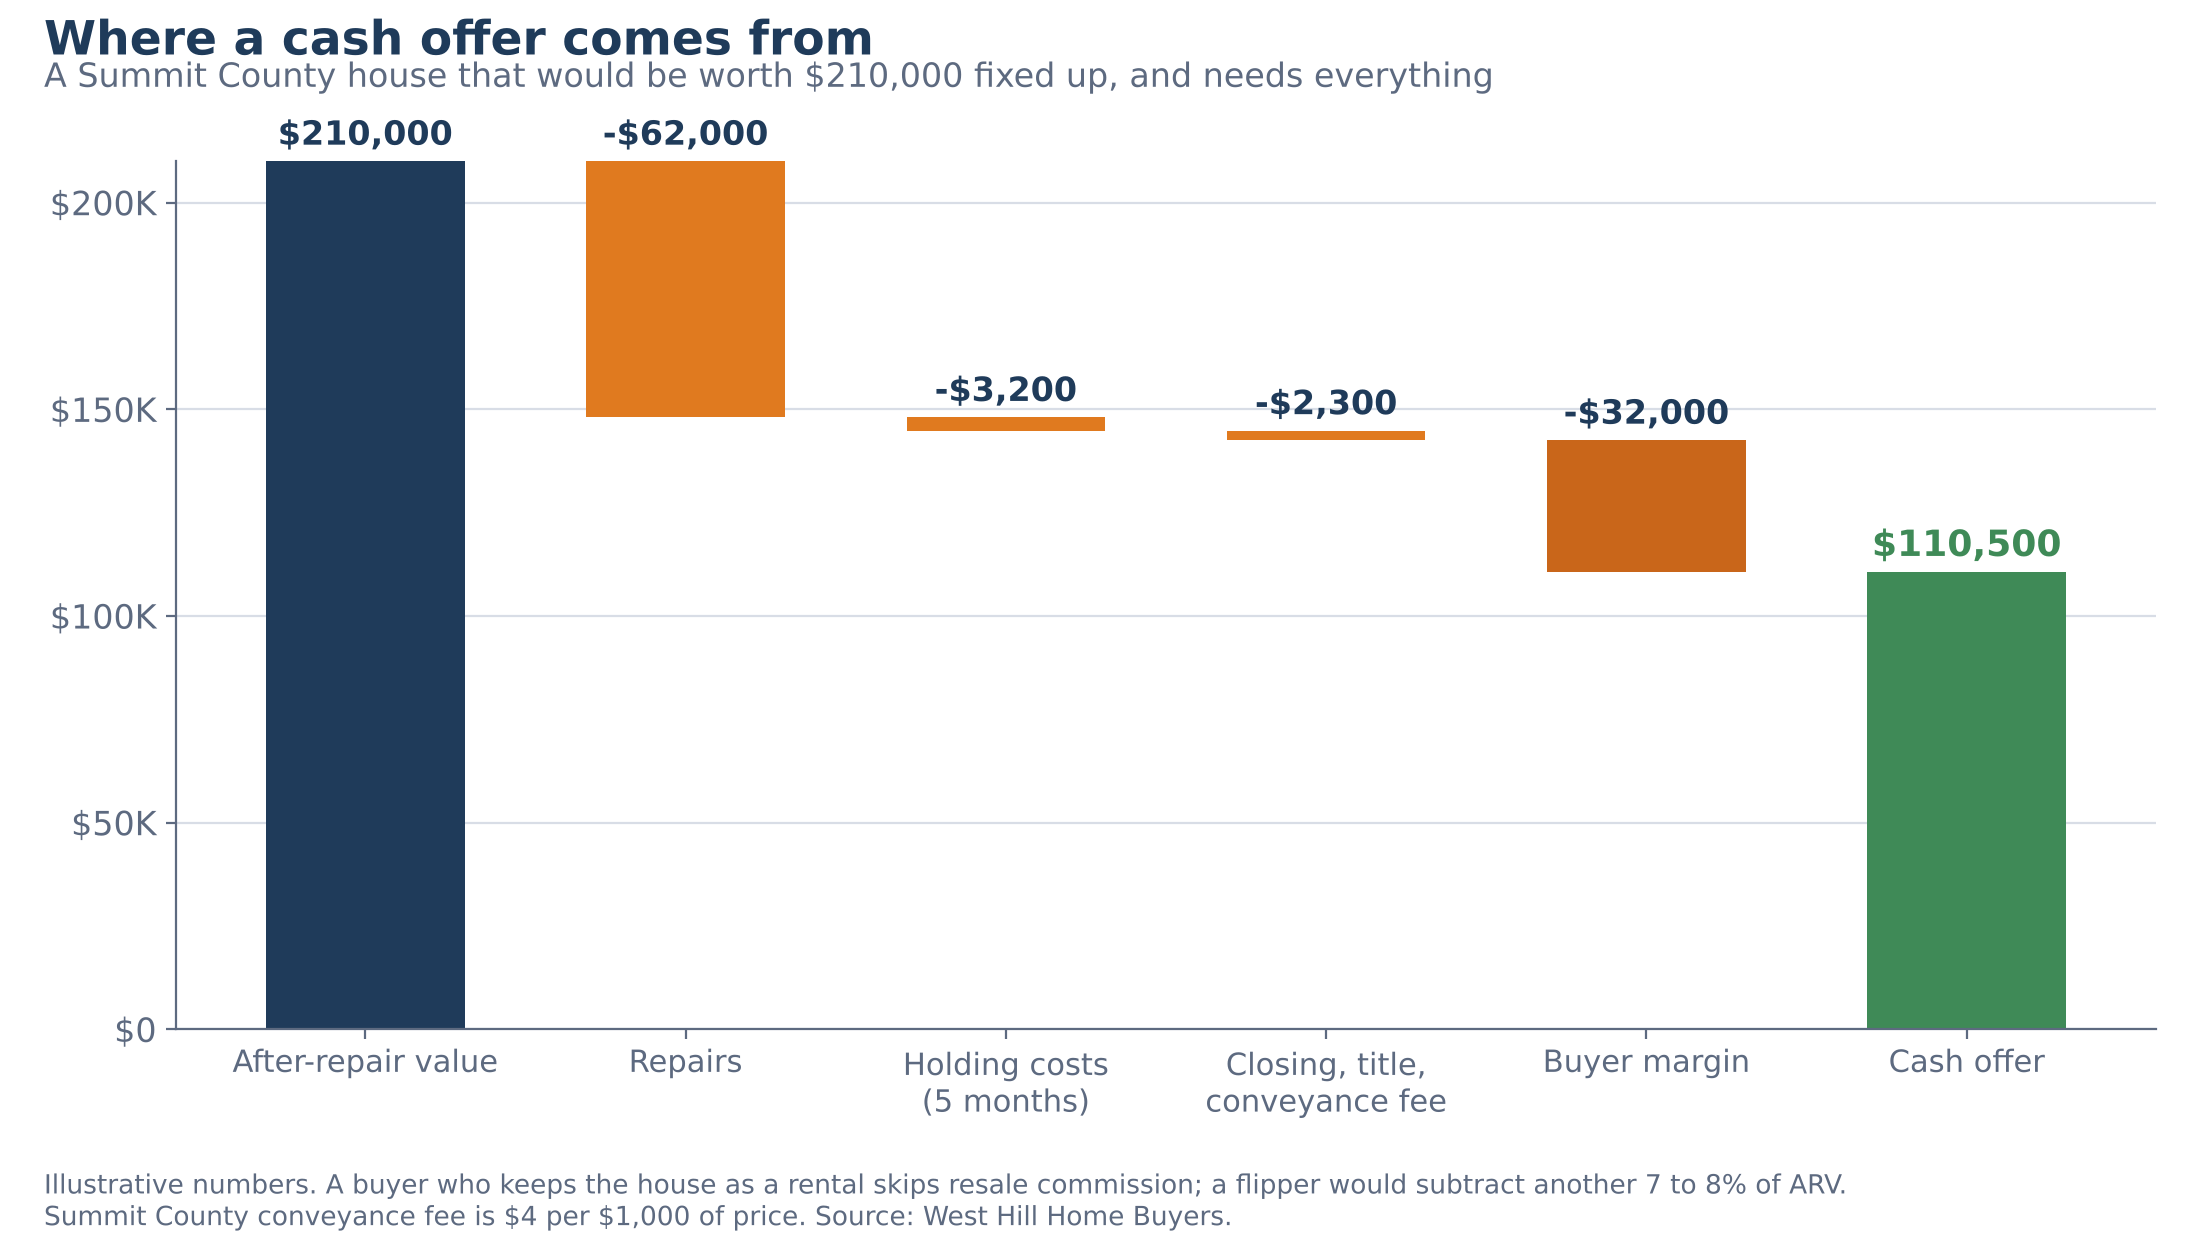
Take a three-bedroom in Cuyahoga Falls that would sell for around $210,000 renovated, which is a normal number in the Falls right now. It needs a roof, a furnace, a kitchen, a bath, a panel, flooring, and paint. Here is roughly how we would look at it:
- After-repair value: $210,000
- Repairs: $62,000
- Holding costs for five months, taxes, insurance, utilities, lawn: about $3,200
- Title, closing, and the Summit County conveyance fee: about $2,300
- Our margin for the capital, the risk, and the work: $32,000
- Offer: around $110,000
A flipper would subtract another $15,000 or so for the commission and closing costs when they resell, which is why a buy-and-hold offer often lands a little higher than a flip offer on the same house. We laid out the whole formula, including the "70% rule" and why it is a shortcut rather than a law, in how cash buyers calculate your offer.
The number that matters when you compare that offer to listing is not the asking price. It is what you net. Listing the same house as-is at $150,000 and actually getting $138,000 after a price cut, then paying $9,000 in commission, $2,000 in seller-paid repairs the buyer's appraiser demanded, and four months of taxes, insurance, and mortgage while it sat, nets you something in the $120,000s, if the buyer's financing holds. If it does not, you are back on the market in month three. The cash offer is lower. The gap is smaller than it looks, and it is certain.
What the process looks like in Ohio
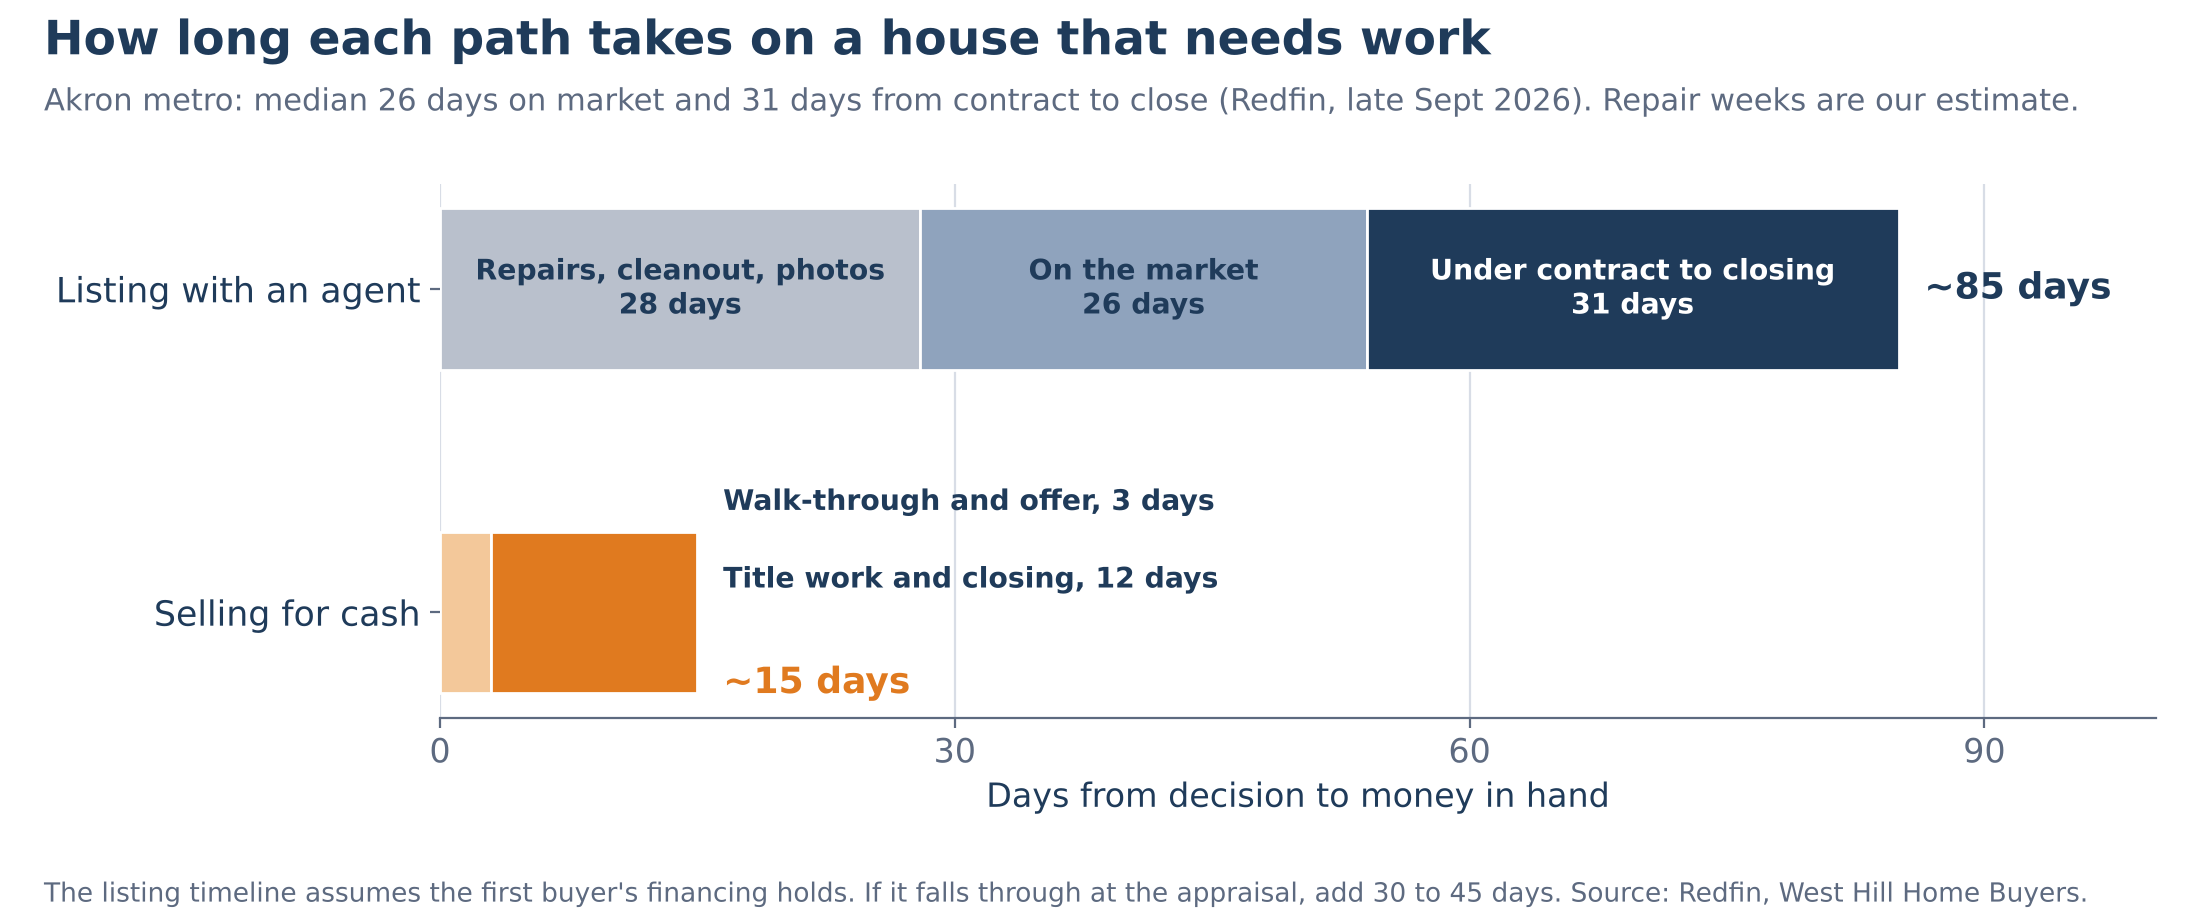
- You call or fill out a form. We ask about the house, the condition, and your timeline. Nobody needs to clean up for us.
- Walk-through. Usually within a couple of days. We look at the roof, the basement, the mechanicals, and the layout. If you are out of state, photos and a FaceTime walk with a neighbor or a relative work fine.
- Written offer. A number, with the repair estimate behind it if you want to see it. No pressure and no expiring countdown. If you want to list it instead, we will tell you so.
- Purchase agreement. A standard Ohio contract. In Ohio most sellers have to complete the Residential Property Disclosure Form unless an exemption applies, like an estate selling through an executor. Fill it out honestly. Nothing on it will scare us off, and it protects you later.
- Title work. A title company runs the search and clears anything that comes up. This is where an inherited house with the deed still in Mom's name gets sorted. If a lien or an open probate turns up, we wait or we help.
- Closing. Typically 10 to 20 days from signing if title is clean. You sign at the title company or with a mobile notary, the deed records, and the money wires to you the same day.
If there is a tenant, we buy with the tenant in place and take over the lease. If you are behind on the mortgage, the payoff comes out of the sale at closing and the rest is yours. We wrote up the Summit County timeline for that in facing foreclosure in Summit County.
When a cash buyer is the wrong call
We will say this plainly because the companies with the billboards will not. If your house is in good shape, financeable, and you can wait 60 to 90 days, list it. You will net more. Cuyahoga Falls and Stow houses that are move-in ready still go in under two weeks even in this market, and a cash buyer cannot compete with a financed family paying full price for a house they want to live in.
A cash sale makes sense when one or more of these is true:
- The house cannot be financed, for any of the reasons above.
- The repairs cost more than you have or more than you want to spend on a house you are leaving.
- You are settling an estate, especially from out of state, and need it done rather than managed. We buy inherited houses in Akron for exactly this reason.
- You are a landlord who is done. Tenants in place, deferred maintenance, maybe several houses at once. We buy rental portfolios in Summit County in one closing, and we wrote a guide for retiring landlords that covers seller financing and 1031 exchanges.
- Something in your life changed and the house is in the way. Divorce, a job in another state, a parent moving in with you. We handle those quietly.
- The market turned and you cannot wait it out. Rates crossed 7% this fall and Akron-area pending sales dropped about 9%. Here is what that means if you are selling this winter.
How to tell a real Ohio cash buyer from a wholesaler
Most of the "we buy houses" calls and letters you get in Summit County are from people who will never own your house. Five questions sort them out fast.
- "Will you be on the deed at closing?" A real buyer says yes without hesitating. A wholesaler changes the subject to "my partners."
- "Can you send proof of funds?" A bank statement or a letter from a lender, dated this month. If they cannot, they are not buying.
- "What is your earnest money, and is it non-refundable after inspection?" A real buyer puts down real money. A wholesaler puts down $100 and an inspection contingency long enough to find someone else.
- "Can I see the repair estimate behind your offer?" Anyone who ran the math can show you the math.
- "What have you bought around here?" Ask for addresses. Look them up on the Summit County Fiscal Office site. The owner of record should be the company you are talking to. Ours is on our work page and on our about page.
One more tell: a real buyer who keeps houses cares about the neighborhood, because they are going to own it for twenty years. We are only buying in Akron, Cuyahoga Falls, and the surrounding Summit County communities, and we live with every one of those decisions.
Questions we get about cash sales in Ohio
Do I pay closing costs? Usually just the conveyance fee, which in Summit County is $4 per $1,000 of the price, and often the buyer picks that up. No commission, no buyer-demanded repair credits, no staging.
Do I have to clean out the house? No. Take what you want and leave the rest. Cleanouts are part of every house we buy.
Can I sell if I am behind on taxes? Yes. Delinquent taxes get paid out of the proceeds at closing. If a tax lien certificate has been sold, the title company handles the payoff.
How fast can you really close? Ten days is possible with clean title and a motivated seller. Two to three weeks is normal. If you need 60 days to move out, that is fine too; we close on your schedule, not ours.
Will you buy a house with a tenant who stopped paying? Yes. We take over the lease and the problem.
Is a cash offer negotiable? Ours is built from a repair estimate, so if you think we have the repairs wrong, show us. Numbers move when the facts move.
If you have a house like this
If you own a house in Summit County that a bank will not finance, or that needs more work than you want to put into it, tell us about it or call (330) 661-9885. We will walk it, give you a number with the math behind it, and tell you honestly if listing it is the better move. Either way you will know what the house is actually worth to the only buyers who can buy it.
Related reading
- How Cash Buyers Calculate Your Offer
- What Happens to Your House After You Sell It to an Investor
- Selling an Inherited House in Akron, Ohio
- Cleanouts, Repair Orders, and Selling a Condemned House in Akron
- The BRRRR Method in Akron: Buying With Cash, Refinancing With a DSCR Loan
West Hill Home Buyers is a local, family-owned company that buys houses in Akron, Cuyahoga Falls, and Summit County for cash, renovates them, and keeps them as rentals. We wrote this because sellers kept asking us what a cash buyer does that a bank cannot, and the honest answer deserved more than a sentence.